Last updated: October 31, 2026
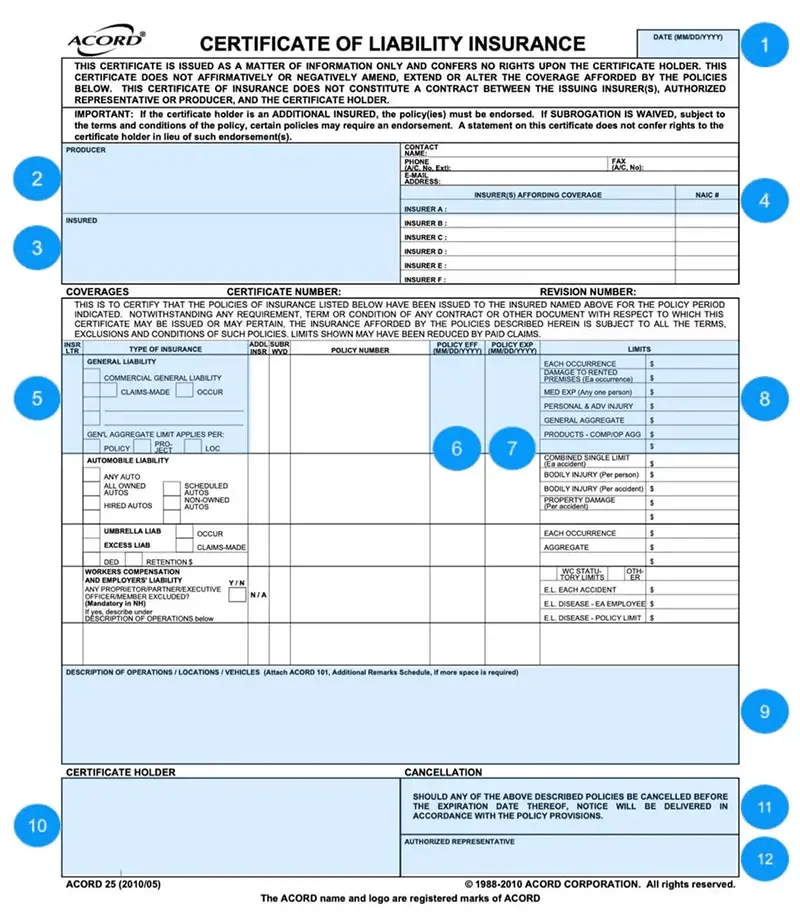
COI stands for certificate of insurance. A COI is a one-page document, usually the ACORD 25, that summarizes a business's insurance: who is insured, which policies are in force, the limits, and the policy dates. The insured's agent or broker issues it, usually at no charge, when a customer, general contractor, landlord, or agency asks for proof of coverage.
A COI shows that coverage existed on the day it was issued. It is not the policy, and it does not confirm the coverage meets your contract.
What is on a COI
A standard ACORD 25 lists the producer (the agent or broker), the insured, the insurance companies, each policy with its number, dates, and limits, checkboxes for additional insured and waiver of subrogation, a description of operations box, and the certificate holder. For a field by field walkthrough, see How to Read a Certificate of Insurance.
How a COI works
- The contract sets requirements. A subcontract, lease, vendor agreement, or permit lists the coverages, limits, and endorsements required.
- You request a COI. Usually before work starts, a tenant moves in, or a permit is issued.
- The vendor's agent issues it. Often within a day. Adding coverage the policy does not have takes longer and can raise the premium.
- You review it. The agent does not check it against your contract. That is the certificate holder's job.
- You track it. Request renewal certificates about 30 days before the earliest expiration date, and keep records long term. Construction claims can surface years after a project closes.
What is a COI in construction?
In construction, a COI is the proof a general contractor collects from every subcontractor before work begins. Many contracts hold site access or payment until an acceptable certificate is on file. Missing certificates also cost money at audit time: a contractor that cannot show its subcontractors carried workers comp can have their payroll added to its own premium. See How COI Tracking Protects You in a Workers Comp Audit.
What a COI does not prove
The ACORD 25 says it is issued for information only and does not change the policies. In practice, a COI does not confirm:
- Endorsements. A checked additional insured or waiver box only shows the item was requested. Only the endorsement confirms it. See additional insured, primary and non-contributory, and waiver of subrogation.
- Available limits. Limits shown may have been reduced by paid claims.
- Current coverage. A certificate does not update if a policy is cancelled or changed.
- Notice of cancellation. A certificate cannot promise notice the policy does not provide. Cancellation for nonpayment can take effect on 10 days' notice in most states.
Certificate holder vs. additional insured
A certificate holder is simply the party the certificate was issued to. That gives you information, not coverage. An additional insured has been added to the policy by endorsement and can make a claim under it. You can be the certificate holder, see the additional insured box checked, and still have no coverage if the endorsement is not on the policy. See ISO Additional Insured Forms.
COI compliance checklist
- The insured name matches the party on the contract.
- Every required coverage is listed, with limits at or above your minimums.
- Policy dates cover the full period of the work.
- Your organization, and any related entities the contract names, are correct.
- Required endorsements are attached, with form numbers and edition dates.
- Insurers meet your minimum rating, such as A.M. Best A- VII.
- The certificate is signed by an authorized representative.
Requirements should match the risk of the work. See COI Requirements by Vendor Type.
How PINS helps
COI tracking sucks, but someone on the team has to do it. In PINS, your team sets requirement templates by vendor type. Vendors and brokers upload documents through a secure link with no login. The PINS AI Assistant reviews each certificate and endorsement, identifies issues, and shows its reasoning. Your team makes the final compliance decision. Renewal requests go out automatically, and every approval, waiver, and exception is logged for audits.
Frequently asked questions
How do I get a certificate of insurance?
Ask your insurance agent or broker, and give them the certificate holder's name and address plus the contract requirements. If your policy already meets them, a certificate is usually issued within a day.
How much does a COI cost?
Agents and brokers usually issue certificates at no charge. If the contract requires coverage or endorsements your policy does not include, adding them can increase your premium.
How long is a certificate of insurance valid?
A COI reflects coverage on the date it was issued, and each policy expires on the date shown. Request a new certificate when any listed policy renews.
What is the difference between a certificate holder and an additional insured?
A certificate holder receives the certificate as information and gains no coverage rights. An additional insured has been added to the policy by endorsement and can make a claim under it.
Does a COI prove insurance compliance?
No. Compliance requires checking the certificate and its endorsements against your contract requirements, then tracking them until the work and any completed operations period end.