Last updated: October 22, 2026
If you are a general contractor operating in today's litigation climate, you already know the truth: when a serious accident happens, fault is only part of the story. Insurance structure, documentation, and risk transfer decide what you pay, and so does whether your file holds up under scrutiny.
Across states like Georgia, Florida, California, Illinois, and Texas, construction-related commercial auto and jobsite injury claims are producing increasingly severe outcomes. Jury verdicts are climbing. Fault percentages are litigated aggressively. And GCs often end up paying far more than they anticipated, even when the subcontractor caused the incident.
The reason is usually the same. Risk transfer fails quietly, in the endorsements, long before the claim.
The problem: risk transfer breaks in the details
On paper, your subcontract likely requires additional insured status, primary and non-contributory wording, a waiver of subrogation, indemnity protections, and specific ISO endorsement forms.
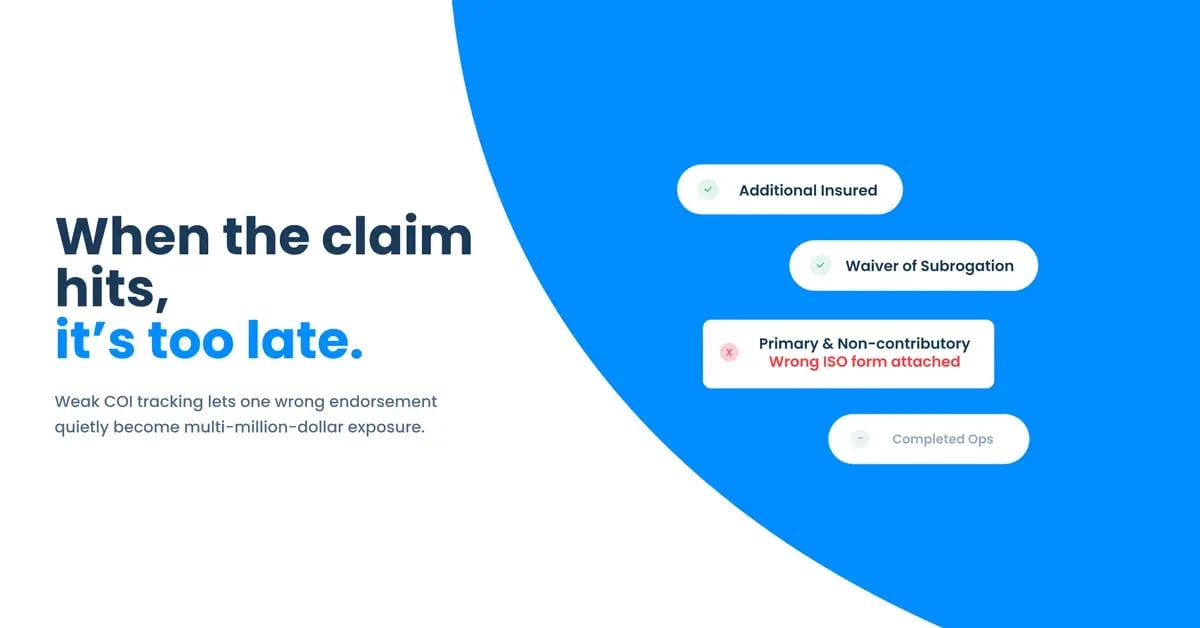
Here is what actually happens in practice. A subcontractor provides a certificate of insurance that looks fine. The endorsement attached is not the required form. The wording says "caused in whole or in part by" instead of the broader "arising out of." Completed operations coverage is missing. Limits are eroded or shared. The umbrella policy does not follow form.
No one catches it until there is a claim.
Once litigation begins, the chance to fix those issues is gone. You are no longer negotiating paperwork. You are negotiating millions.
For a practical checklist of what to require and how to verify each item, see What Endorsements Should I Require from Subcontractors?
Why this matters more today
Even in states that have eliminated pure joint and several liability, litigation strategy often shifts fault toward the deepest pocket in the room.
If your subcontractor's insurance does not properly extend coverage to you, your own CGL and umbrella become primary. Your loss history absorbs the hit. Your EMR and insurance costs go up. Your risk transfer strategy collapses.
The cost is not one claim. It is your long-term insurance economics.
The fix: control the paper before the claim
This is where most GCs are exposed. COI tracking is often a manual process handled by one person who is already stretched thin.
Manual review misses endorsement language. It skips form number checks. It overlooks completed operations coverage. It relies on PDFs that nobody reads in detail, and it leaves no structured audit trail.
When a serious claim goes to litigation, defense counsel asks one question: did you verify compliance before allowing the sub on site? If the answer is unclear, the narrative shifts fast.
How PINS helps GCs enforce risk transfer
AI-assisted endorsement review
The PINS AI Assistant reads the actual wording on additional insured, primary and non-contributory, and waiver of subrogation endorsements, along with completed operations coverage and limits. It checks each one against your contract requirements, identifies issues, and shows its reasoning with a link to the source page. Your team reviews the findings and makes every call.
Contract-specific requirements
Each subcontract can carry different insurance requirements. In PINS, your team builds requirement templates by vendor type or risk profile and assigns them to each sub, or PINS AI reads the contract and builds the requirements from it. Every certificate is checked against the exact requirements for that sub.
An audit trail that supports your defense
If a claim goes to litigation, documentation matters. PINS keeps a time-stamped review history, deficiency notices, approvals, waivers, and vendor communication on each record. That history becomes part of your defense.
Renewals that do not depend on memory
Risk transfer only works if it is enforced over the life of the project. PINS sends renewal requests before policies expire, collects updated documents through a no-login upload link, and shows compliance status to the project team, including inside Procore and Vista. A lapsed policy shows up when it lapses, not after a claim.
Prevention is an underwriting strategy
In high-severity litigation environments, the companies that fare best are not the ones who had a contract. They are the ones who can prove they enforced it: reviewed endorsements, validated coverage, monitored compliance, and acted consistently.
GCs are scrutinized not just by plaintiffs, but by their own insurers. A strong compliance program protects upstream risk transfer, reduces claim severity exposure, and gives you a better story at renewal.
Bottom line
You cannot prevent every accident. You can control whether your risk transfer works when it matters most.
The difference between a defensible claim and a catastrophic one often comes down to a single endorsement that was or was not reviewed. Make sure that review happens before the job starts, because once the claim hits, it is too late.
For how general contractors run this day to day, see COI tracking for construction.
Frequently asked questions
What is risk transfer in construction and why does it fail?
Risk transfer is the process of shifting liability from one party to another through contractual insurance requirements. In construction, GCs transfer risk to subcontractors by requiring them to carry specific insurance and name the GC as an additional insured. It fails when the endorsements are missing, use the wrong wording, or cover a narrower scope than the contract requires. The certificate may look compliant while the underlying coverage is not.
What endorsements do GCs need from subcontractors to protect risk transfer?
At minimum, additional insured endorsements covering both ongoing and completed operations, primary and non-contributory language on the GL policy, and waiver of subrogation on both GL and workers compensation policies. Each requires a separate endorsement document. The certificate of insurance does not confirm any of these are in place. Only the endorsement confirms the coverage.
What is a nuclear verdict and how does it affect GCs?
A nuclear verdict is a jury award far larger than the actual damages in a case, often driven by litigation strategy that targets the deepest pocket in the room. For GCs, this matters because if subcontractor insurance does not properly extend coverage through endorsements, the GC's own policy becomes primary. The GC absorbs the claim, the loss history, and the long-term premium impact.
How does an audit trail help in construction litigation?
When a serious claim goes to litigation, defense counsel examines whether the GC verified compliance before allowing the subcontractor on site. A documented audit trail, including time-stamped review history, deficiency notices, approval records, and vendor communication, shows that compliance was actively managed. Without it, the narrative shifts toward the GC regardless of fault.